Massachusetts Has No Insurance Mandate
It's easy to assume that if you own an ATV or UTV in Massachusetts, you'll need to carry insurance, just like you would for your car. After all, these machines can be powerful, and accidents happen. But the reality in the Bay State can be a bit surprising for many riders. This guide is here to clear up that confusion, explain the actual rules, and help you understand the significant implications—both good and bad—of Massachusetts' unique approach to off-road vehicle insurance.
The Common Misconception: Why Many Expect ATV Insurance is Required
When you think about owning any kind of vehicle, especially one you're going to operate, insurance is usually one of the first things that comes to mind. We're conditioned to it, and for good reason. Massachusetts has some pretty stringent laws about automobile insurance, and it makes sense to assume those same protective measures would extend to ATVs and UTVs. But off-highway vehicles (OHVs) operate in a different legal landscape, one that often catches new and even experienced riders off guard.
Drawing Parallels to Car Insurance Requirements
Think about buying a car in Massachusetts. Before you can even drive it off the lot or register it with the RMV, you absolutely have to have an insurance policy in place. It's a non-negotiable part of vehicle ownership here. This mandatory coverage, typically including liability, personal injury protection, and uninsured motorist coverage, is designed to protect everyone on the road. It ensures that if you cause an accident, there's a financial safety net for anyone you might injure or any property you might damage. This comprehensive system is deeply ingrained in our understanding of vehicle responsibility, so when folks turn their attention to ATVs, they often apply the same logic. They figure, "If my sedan needs it, surely my quad, which can go just as fast and sometimes be ridden in even more unpredictable terrain, needs it too." It's a natural leap of logic, but it's not quite right when it comes to off-road machines in Massachusetts.
Understanding Massachusetts' Focus on Registration and Safety
Instead of focusing on mandatory insurance, Massachusetts law, specifically Chapter 90B, places its emphasis heavily on registration and rider safety. Before you even think about hitting a DCR trail, your ATV or UTV needs to be properly registered with the Massachusetts Environmental Police. This isn't just a suggestion; it's a legal requirement, and one that carries penalties if ignored. [Massachusetts Penalties for Riding Unregistered] can be steep, and an officer will certainly check for your sticker. The fees collected from these registrations, by the way, go directly back into maintaining and creating OHV trails, which is pretty neat. [Massachusetts Registration Fees Fund Trails]
Beyond registration, the state has a strong commitment to rider safety, especially for youth. We have laws like Sean's Law, which places strict age and engine size limits on riders, and a mandatory helmet law for everyone, regardless of age. [Massachusetts Helmet Law for Every Rider] There are also specific rules about where you can and cannot ride, like the [Massachusetts Rules for Riding Private Land] and prohibitions against riding on public ways. The thinking here is that by regulating who can ride, where they can ride, and ensuring machines are identifiable and safe to operate, many of the risks are mitigated at the source, rather than through financial indemnification. It's a different approach, prioritizing preventative safety measures and trail management over mandatory financial protection from an insurance policy.
The Undeniable Truth: Massachusetts Has No Insurance Mandate for OHVs
Let's cut right to the chase because this is the core of the matter: Unlike cars, trucks, and motorcycles, Massachusetts does not require ATV or UTV owners to carry liability insurance or any other form of insurance to register or operate their off-highway vehicles. You won't be asked for proof of insurance when you register your machine, and you won't get a ticket from an Environmental Police officer for not having it. This fact often surprises people, and it's essential to understand exactly what this means, and what it doesn't mean.
What Chapter 90B Says (and Doesn't Say) About Insurance
The primary body of law governing ATVs and UTVs in Massachusetts is Chapter 90B of the Massachusetts General Laws. This chapter covers a wide range of topics related to recreational vehicles, including snowmobiles and OHVs. It meticulously details registration requirements, age restrictions for riders, equipment standards (like brakes and mufflers), and where these machines can legally be operated. You'll find sections dedicated to things like carrying your [Massachusetts Registration Cards Carried on Board], proper decal placement, and even the rules for crossing public ways. [The ATV Law Lives in Chapter 90B] is a crucial document for any rider.
However, if you pore over Chapter 90B, you'll notice a glaring omission: there's no mention of mandatory insurance. No requirement for minimum liability coverage, no stipulation for personal injury protection, nothing. The law simply doesn't address it as a prerequisite for registration or legal operation. This isn't an oversight; it's a deliberate choice in how the state regulates off-road vehicles. The focus is heavily on ensuring machines are registered, safe to operate, and used responsibly within designated areas, rather than mandating financial protection against accidents through insurance. This silence in the law is the definitive answer to the question of whether insurance is required: it is not.
The Environmental Police's Role in Enforcement
Since there's no insurance mandate, the Massachusetts Environmental Police (MEP), who are responsible for enforcing OHV laws, don't check for insurance. Their focus during a trailside stop will be on confirming proper registration, checking for compliance with age and safety equipment laws, and ensuring you're riding in an authorized area. They'll want to see your registration card, check your decal, and observe whether you're following the safety rules.
For example, if you're riding with a youth, an officer will definitely be looking to see if the child meets the [Massachusetts ATV Age Requirements] and is wearing a proper helmet. They'll also be verifying that your machine's VIN matches your registration paperwork. If you're involved in an accident, the MEP will investigate to determine fault and ensure all safety regulations were followed, and they'll file an [Massachusetts Accident Reporting Rules] report. However, the presence or absence of an insurance policy on your ATV or UTV will not be part of their enforcement checklist or citation process for operating an unregistered or unsafe vehicle. Their role is about public safety and resource protection, not about mediating financial liabilities between private parties after a mishap.
The Significant Risks of Riding Uninsured in Massachusetts
While it's true that Massachusetts doesn't mandate insurance for your ATV or UTV, that doesn't mean riding without it is consequence-free. In fact, choosing to forgo optional insurance can expose you to some very significant financial risks that could derail your finances and cause a lot of stress. It's crucial to understand these potential pitfalls before deciding to ride completely uninsured.
Financial Exposure in Case of an Accident
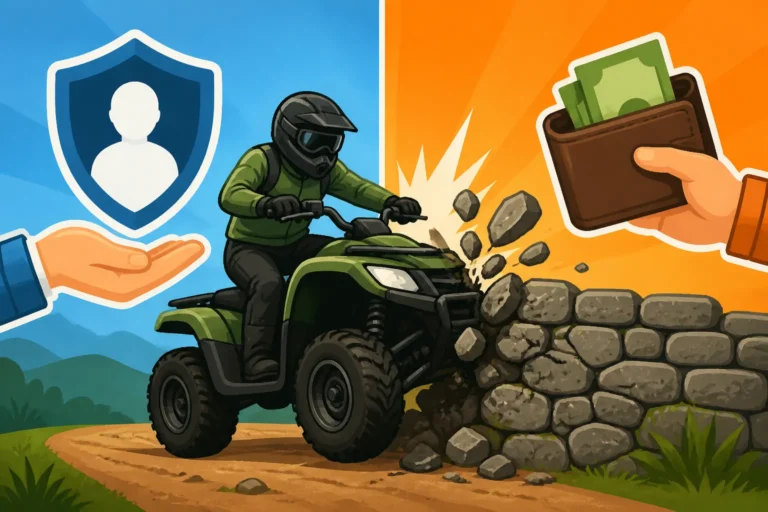
Imagine you're out on the trails at October Mountain State Forest, having a blast. Suddenly, a blind corner, a moment of misjudgment, and you collide with another rider. Thankfully, everyone is okay, but their brand-new side-by-side now has a bent frame and a shattered headlight. Or perhaps you slide off a muddy section and take out a section of a stone wall on private land adjacent to the trail. What happens then? If you don't have insurance, you are personally responsible for the full cost of those damages. This isn't just a little fender bender on a road; repairs for off-road machines, especially UTVs, can quickly climb into the thousands of dollars.
Without liability coverage, that bill comes straight out of your pocket. This means draining your savings, going into debt, or potentially even facing a lawsuit if the damages are substantial and you can't pay. For many families, an unexpected bill for $5,000, $10,000, or even more for vehicle repairs or property restoration could be absolutely devastating. This is the stark reality: "no mandate" means "no safety net" from an insurer when you are at fault for causing damage to someone else's property or machine. Consider how much you're willing to lose if something goes wrong. This is where [Massachusetts Insurance Worth Buying Anyway] truly comes into play.
Personal Liability for Property Damage or Injury to Others
Beyond just damaging another machine, what if your accident results in injuries to another person? Or what if you accidentally damage someone's private property, like a fence line, a shed, or even landscaping? Massachusetts law states that [Who Pays When a Rider Hits a Stone Wall] is ultimately the responsible party – you. If you're riding on sanctioned trails and have an incident, you're not riding in a vacuum of legal immunity. You're still subject to general liability laws. If someone is injured due to your negligence, they have every right to pursue legal action against you for medical expenses, lost wages, and pain and suffering.
These kinds of claims can run into the tens or even hundreds of thousands of dollars. Without liability insurance, you would be personally responsible for these costs. This could mean a judgment against you, garnishing wages, or even placing a lien on your assets. It’s not just about what you might have to pay out-of-pocket for repairs; it’s about protecting your entire financial future from unforeseen accidents. Even if you're the safest rider out there, accidents can happen, and sometimes, they involve other people. This risk is perhaps the single biggest reason why many riders choose to voluntarily insure their OHVs.
Loss or Theft of Your Machine Without Coverage
It's a nightmare scenario for any owner: you wake up one morning, or return from a long day at work, and your pride and joy—your ATV or UTV—is gone. Stolen from your garage, your shed, or even the back of your truck. These machines are valuable assets, and unfortunately, they are also targets for thieves. Without comprehensive or theft coverage, a stolen machine is simply a total loss. You're out the entire purchase price, any money you put into accessories, and you have nothing to show for it but a police report.
Consider the investment you've made. Whether it's a youth quad, a sport ATV, or a multi-passenger UTV, these machines represent a significant chunk of change. If you've accessorized it with high-performance parts from a brand like SuperATV, that investment grows even larger. [Massachusetts Theft Coverage in a Garage] can make the difference between replacing your machine and simply absorbing the loss. Similarly, if your machine is damaged beyond repair in an accident that isn't your fault (or is your fault but you want to cover your own machine), collision coverage would step in. Without it, you're looking at potentially thousands of dollars in repairs or the complete loss of your investment.
Here's a quick comparison of the risks:
| Scenario | Riding Uninsured | Riding With Optional Insurance (e.g., Liability, Comprehensive, Collision) |
|---|---|---|
| Damage to Another's Property | Personally responsible for all repair costs, potential lawsuit. | Insurer covers costs up to policy limits; you pay deductible. |
| Injury to Another Person | Personally responsible for medical bills, lost wages, pain & suffering; major lawsuit risk. | Insurer covers costs up to policy limits; you pay deductible. |
| Theft of Your Machine | Total financial loss of your machine and accessories. | Insurer covers replacement cost up to policy limits; you pay deductible. |
| Damage to Your Own Machine | Personally responsible for all repair costs, or absorb total loss. | Insurer covers costs up to policy limits; you pay deductible. |
| Medical Bills for Yourself | Personally responsible for all medical bills from an OHV accident. | Medical payments coverage can help with your own treatment costs. |
Types of Optional OHV Insurance You Can Get (and Why You Should Consider Them)
Even though Massachusetts doesn't require ATV or UTV insurance, a wide range of optional policies are available, specifically designed for off-highway vehicles. These aren't just scaled-down versions of car insurance; they're tailored to the unique risks and uses of ATVs and UTVs. Deciding to purchase one of these policies is a smart move for many riders, offering peace of mind and crucial financial protection in a variety of situations.
Liability Coverage: Protecting Your Wallet from Others' Damages
This is often the most important type of insurance to consider, and it's the foundation of most vehicle policies. Liability coverage protects you financially if you're found responsible for an accident that causes damage to someone else's property or injuries to another person. It typically comes in two parts:
- Bodily Injury Liability: This covers medical expenses, lost wages, and pain and suffering for anyone you injure in an accident where you are at fault. Imagine a scenario where you misjudge a turn on a shared trail and accidentally run into a hiker, causing them a serious leg injury. Without bodily injury liability, those medical bills, potential rehabilitation costs, and lost income for the injured party would fall squarely on your shoulders. With coverage, your insurance company would step in to cover these costs up to your policy limits.
- Property Damage Liability: This covers the cost of repairing or replacing someone else's property that you damage in an accident. This could be another ATV, a UTV, a fence post, a shed, or even a parked vehicle if you somehow managed to get off the trail and hit one. Repairing a damaged side-by-side or replacing a section of fencing can be incredibly expensive. This coverage ensures that you're not personally on the hook for those costs. It's truly a shield for your personal assets against claims from others.
Even if you're the most cautious rider, accidents happen, and having liability coverage means you won't have to face potentially ruinous financial consequences if you make a mistake.
Comprehensive and Collision: Protecting Your Own Investment
While liability protects others, comprehensive and collision coverages are all about protecting your machine and your financial investment in it. These are the coverages that will help you repair or replace your own ATV or UTV.
- Collision Coverage: This pays for damages to your own ATV or UTV if it's involved in a collision, regardless of who is at fault. This could be hitting a tree, rolling over, colliding with another off-road vehicle, or even backing into something at your staging area. Given the rough nature of off-road riding, collision damage is a very real possibility. If you've invested significantly in your machine, perhaps customizing it with accessories from SuperATV like a heavy-duty bumper or a winch, collision coverage ensures that these components are also protected in an accident, not just the base machine.
- Comprehensive Coverage: This is designed to cover damages to your ATV or UTV that are not caused by a collision. Think of it as protection against a wide range of other perils. This includes theft, vandalism, fire, certain natural disasters (like floods or hail), and even hitting an animal. If your quad is stolen from your garage or vandalized while parked at a trailhead, comprehensive coverage would help cover the cost of replacement or repairs. [Massachusetts Comprehensive Coverage for a Quad] is invaluable for protecting your investment against these non-collision risks that are unfortunately all too common.
These two coverages are essential for anyone who sees their ATV or UTV as a valuable asset that they want to protect, not just from accidents, but from all the other unpredictable things that can happen.
Uninsured/Underinsured Motorist and Medical Payments
Beyond the core liability and physical damage coverages, there are a few other types of optional insurance that can add crucial layers of protection:
- Uninsured/Underinsured Motorist (UM/UIM): While you might choose to carry insurance, remember that many other ATV riders in Massachusetts won't. If you're involved in an accident with another rider who is at fault but has no insurance (uninsured) or insufficient insurance (underinsured) to cover your damages and injuries, UM/UIM coverage would kick in to protect you. This means you won't be left with massive bills even if the at-fault party can't pay. This is especially important given the lack of a statewide mandate.
- Medical Payments (MedPay): This coverage helps pay for medical expenses for you and your passengers, regardless of who caused the accident. This can be a lifesaver, covering things like ambulance fees, hospital stays, doctor visits, and even funeral expenses in the most tragic circumstances. Unlike health insurance, which can have high deductibles and co-pays, MedPay offers a swift way to get medical bills paid without extensive negotiation or claims processing. This is vital if you or a loved one is injured while riding, as off-road accidents can often lead to serious injuries.
- Accessory Coverage: If you've spent a lot of money customizing your machine with aftermarket parts like specialized tires, a sound system, plows, or a full lighting kit from a brand like SuperATV, you'll want to ensure these are covered. Standard policies might only cover factory components. Many insurers offer additional accessory coverage that allows you to specify the value of your aftermarket additions, ensuring they're protected too.
These additional coverages round out a comprehensive insurance plan, offering protection not just for your liability to others, but also for your own well-being and the full value of your machine and its custom parts.
Factors Influencing Optional ATV/UTV Insurance Costs
Deciding to get optional insurance is one thing, but understanding what influences the price you'll pay is another. Insurance premiums for ATVs and UTVs aren't a flat rate; they vary widely based on several key factors. Knowing these can help you shop smarter and find a policy that fits both your needs and your budget.
Your Machine's Value, Type, and Accessories
One of the biggest drivers of your insurance premium is the machine itself. A brand-new, high-performance UTV with a powerful engine and multiple seats will almost always cost more to insure than an older, smaller, single-rider ATV. Here's why:
- Purchase Price and Replacement Value: Insurers look at how much it would cost to replace your machine if it were stolen or totaled. A higher initial purchase price translates to a higher potential payout for the insurance company, thus a higher premium.
- Type of Machine: Sport ATVs and utility UTVs, for instance, have different risk profiles. Sport models might be associated with higher speeds and more aggressive riding, potentially leading to more claims. Utility models, while perhaps slower, can be involved in work-related accidents or carry more passengers. Side-by-sides, being larger and heavier, often cause more significant damage in a collision and have higher repair costs.
- Engine Size and Horsepower: More powerful engines often correlate with higher speeds and, potentially, higher risk.
- Accessories and Modifications: If you've invested in aftermarket parts, like a lift kit, heavy-duty suspension, or specialized tires from a company like SuperATV, you'll need to declare these to your insurer. While these enhance your riding experience, they also increase the total value of your machine. You'll likely pay a bit more to ensure these additions are covered, but it's well worth it to protect your full investment. Failing to declare them could mean they aren't covered if something happens.
Your Riding Habits and Experience
Just like with car insurance, your personal profile as a rider plays a significant role in determining your premiums.
- Riding Experience: Insurers often see experienced riders as lower risk. If you've been riding for many years without incident, you might qualify for better rates than a brand-new rider.
- Age and Gender: While less impactful than experience, these demographic factors can sometimes influence rates, reflecting broader statistical trends in accident rates.
- Accident and Claims History: This is a big one. If you've filed previous claims on an OHV policy, or even had at-fault accidents on other vehicle policies, your rates will likely be higher. A clean record, on the other hand, can help keep costs down.
- Where You Ride: Some insurers might ask about your typical riding environment. Do you stick to designated DCR trails, or do you frequent private lands? While less common, certain high-risk riding behaviors (like competitive racing, if disclosed) could also affect your rates or require specialized coverage.
- Storage Location: Where and how you store your machine matters. A machine kept in a secure, locked garage or shed is generally seen as less of a theft risk than one parked openly in a driveway. [Massachusetts Theft Coverage in a Garage] is often explicitly tied to the security of your storage.
Deductibles and Coverage Limits
These are two of the most direct ways you can influence your premium.
- Deductible: This is the amount of money you agree to pay out-of-pocket before your insurance coverage kicks in for a claim. Common deductibles might be $250, $500, or $1,000. Choosing a higher deductible typically results in a lower monthly or annual premium, because you're taking on more of the initial financial risk yourself. Conversely, a lower deductible means higher premiums but less out-of-pocket expense if you need to file a claim.
- Coverage Limits: These are the maximum amounts your insurance company will pay for a covered loss. For liability, this would be represented by numbers like 25/50/25 ($25,000 for bodily injury per person, $50,000 for bodily injury per accident, $25,000 for property damage). For comprehensive and collision, it's typically the actual cash value of your machine up to a certain maximum. Higher coverage limits offer more protection but will lead to higher premiums. You'll need to weigh the level of risk you're comfortable with against the additional cost. Many riders opt for higher liability limits to protect their assets, especially if they own a home or have significant savings.
- Bundling: Often, you can get a discount by bundling your ATV/UTV insurance with other policies, like your home, auto, or motorcycle insurance, from the same provider. It's always worth asking about multi-policy discounts.
By understanding these factors, you can make informed choices about your policy, balancing comprehensive protection with an affordable premium. [Massachusetts Optional Insurance Costs] can vary greatly, so getting multiple quotes is key.
When Insurance Becomes Indirectly Required or Highly Recommended
Even though Massachusetts law doesn't mandate ATV/UTV insurance, there are several real-world situations where you'll find yourself needing it, or at least strongly encouraged to have it. Ignoring these can prevent you from enjoying your machine or even put your financial well-being at risk.
Lender Requirements for Financed Machines
This is one of the most common scenarios where insurance becomes non-negotiable. If you didn't pay cash for your ATV or UTV and instead financed it through a bank, a credit union, or the manufacturer, your lender will almost certainly require you to carry full coverage insurance. Why? Because until the loan is paid off, the lender technically owns a stake in your machine. They want to protect their investment.
If your machine is stolen, damaged beyond repair, or totaled in an accident, the lender wants assurance that their financial interest will be protected. They don't want to be left holding the bag for a loan on a machine that no longer exists or can't be repaired. This typically means carrying both comprehensive and collision coverage, often with specific deductible limits set by the lender. You'll need to provide proof of this insurance to your lender, and if your coverage lapses, they may purchase their own (often more expensive) policy and pass the cost directly to you. This is a crucial point for anyone looking at [Financing an Off-Road Machine in Massachusetts].
Private Riding Parks and Organized Events
While Massachusetts DCR forests like October Mountain or Beartown don't require you to show proof of insurance to enter, many private riding parks, off-road recreation areas, or organized events (like poker runs, charity rides, or races) often have their own rules. These entities frequently require riders to show proof of liability insurance before they'll allow you to participate.
The reason is simple: these parks and event organizers are trying to mitigate their own risks. If an accident occurs on their property or during their event, and you, as a participant, are at fault for causing injury or damage, they want to ensure there's an insurance policy that can cover the costs, protecting them from potential lawsuits. They might ask for a minimum liability coverage amount, and you'll typically have to sign a waiver. Before heading to any private park or event, always check their specific insurance requirements. If you show up without the proper coverage, you'll likely be turned away, wasting your time and gas.
Landowner Requirements for Private Land Access
Many riders enjoy the privilege of riding on private land, whether it's their own property, a friend's expansive woodlot, or a local farm that allows OHV access. However, accessing private land, especially land that doesn't belong to you, usually requires explicit permission. [Massachusetts Requires Written Permission] from the landowner. A considerate landowner, particularly one who understands the potential liabilities, might ask you to carry liability insurance.
Think about it from their perspective: if you're riding on their property and accidentally cause damage to their fences, equipment, or even injure someone else (or yourself, leading to a premises liability claim), they could be held responsible if you don't have insurance. To protect themselves, some landowners will stipulate that any rider on their property must have valid liability insurance. They may even ask for proof, or for you to add them as an "additional insured" on your policy, which simply means they're also protected by your policy in certain circumstances. Respecting a landowner's request for insurance is not just about legal protection; it's about maintaining a good relationship and ensuring continued access to valuable private riding areas.
Understanding Massachusetts' Approach to OHV Safety vs. Financial Responsibility
It's clear that Massachusetts takes a different route when it comes to regulating ATVs and UTVs compared to other vehicles. This distinction isn't arbitrary; it reflects a specific philosophy regarding how off-highway recreation should be managed in the state. Understanding this approach helps to explain why there's no insurance mandate and what the state prioritizes instead.
Prioritizing Rider Safety Through Education and Equipment Laws
Massachusetts law enforcement and regulatory bodies, particularly the Environmental Police and the Department of Conservation and Recreation (DCR), focus heavily on proactive safety measures. Instead of mandating insurance as a financial backstop after an incident, the state tries to prevent incidents from happening in the first place through a comprehensive set of regulations:
- Age and Engine Size Restrictions: One of the most significant pieces of legislation is [Sean's Law: The 2010 Ban Named for a Boy], which severely restricts who can ride and what size machine they can operate. Riders under 14 are generally banned, and strict engine size limits apply to those between 14 and 16. This is a direct effort to remove the most vulnerable and inexperienced riders from potentially dangerous situations.
- Mandatory Safety Certificates: For riders under 18, a Massachusetts OHV Safety Certificate is required to operate on public lands. This involves both a classroom and a hands-on skills test, ensuring that young riders have received proper training.
- Helmet Laws: Every single rider, regardless of age, must wear a helmet. This is a fundamental safety measure proven to reduce serious head injuries. [Massachusetts ATV Helmet Law] is non-negotiable.
- Equipment Requirements: ATVs and UTVs must meet certain equipment standards, including working brakes, mufflers (to control noise), and lights for night riding. These rules are designed to ensure machines are in safe operating condition.
- Designated Riding Areas: The state carefully designates where OHVs can and cannot be ridden, primarily restricting them to specific DCR trails in state forests. This helps to manage conflict with other users and reduce the likelihood of accidents in inappropriate areas.
This entire framework is built on the premise that a well-regulated, well-trained, and well-equipped rider operating on appropriate trails is the safest rider. The state's investment is in this preventative approach, aiming to minimize accidents rather than just dealing with the financial aftermath.
The Absence of a State-Run Financial Responsibility System for OHVs
For automobiles, Massachusetts has a compulsory insurance system that is designed to ensure financial responsibility. If you cause an accident, the system is in place to make sure there's money to cover the damages and injuries. This is a core tenet of motor vehicle registration.
For OHVs, however, that state-mandated financial safety net simply doesn't exist. There's no requirement for a bond, a cash deposit, or an insurance policy to prove you can cover potential damages. This means that if you're involved in an accident with an uninsured rider who causes damage or injury, you could be left with significant costs yourself, unless you have your own uninsured motorist coverage. If you hit an uninsured rider who is at fault, [What Happens to Your Insurance After a Collision] could involve you paying your deductible and then your insurer attempting to recover funds from the at-fault party, which can be a long and difficult process if they have no assets or insurance.
The state's perspective seems to be that off-road riding is a recreational activity with inherent risks, and individual riders are largely responsible for managing their own financial exposure. While the state aims to keep everyone safe through regulations, it doesn't extend the same level of financial protection to OHV users that it does to traditional motor vehicle operators. This places a greater onus on individual riders to make informed decisions about optional insurance coverage to protect themselves and their assets. This is a key distinction between [Massachusetts ATV Laws Under Chapter 90B] and the rules governing on-road vehicles.
Making an Informed Decision About ATV Insurance
Ultimately, whether or not to purchase insurance for your ATV or UTV in Massachusetts is a personal choice. Since it's not legally mandated, you have the freedom to decide. However, making an informed decision means thoroughly weighing the potential costs against the significant risks involved, and understanding how to find the right coverage if you choose to get it.
Weighing the Costs Against the Potential Risks
The primary reason many riders opt out of insurance is the additional cost. No one wants another monthly bill. However, it's essential to look beyond the immediate expense and consider the potential long-term financial ramifications of not having coverage.
- Cost of an Accident: How much could you realistically afford if you caused $10,000 in damage to another machine or $50,000 in medical bills for an injured person? Could you replace your own $8,000 UTV if it were stolen or destroyed? For most people, these figures represent a substantial financial hit, far outweighing the annual cost of an insurance premium.
- Peace of Mind: There's a tangible value to peace of mind. Knowing that you're protected from major financial setbacks allows you to enjoy your riding without constantly worrying about "what if."
- Your Financial Situation: If you have significant assets (a home, substantial savings, etc.), liability insurance becomes even more critical. These assets could be at risk in a lawsuit if you're found responsible for a major accident. If you're [Riding Under the Influence on a Berkshire Trail] and cause an accident, your liabilities could be enormous, and insurance might not even cover incidents involving illegal activity.
- Usage Frequency: If you ride frequently, the chances of an incident occurring naturally increase, making insurance a more prudent investment. If your machine is stored most of the year and only sees occasional use on your private property, your risk profile might be lower, though still not zero.
Before dismissing insurance purely on cost, calculate what you could stand to lose in a worst-case scenario. Often, the relatively small annual premium pales in comparison to the potential out-of-pocket expenses. [Massachusetts Cost of Ownership Year One] often includes items that people forget, and insurance should be part of that budget calculation.
How to Shop for the Right Policy
If you decide that optional insurance is the right choice for you, the next step is to find a policy that offers the right balance of coverage and affordability.
- Assess Your Needs: What kind of coverage is most important to you? Is it liability to protect your assets? Comprehensive/collision to protect your machine? Medical payments for yourself and passengers? Or a combination? Consider how you use your machine, where you ride, and your personal financial risk tolerance.
- Gather Information: You'll need details about your ATV or UTV (make, model, year, VIN), your riding experience, and information about any modifications or accessories you've added (especially from brands like SuperATV).
- Get Multiple Quotes: Don't just go with the first quote you receive. Contact several insurance providers. Many major insurance companies that offer auto or home insurance also offer OHV policies, such as Progressive, GEICO, Allstate, State Farm, and others. Independent insurance agents can also be very helpful, as they can shop around with multiple carriers on your behalf to find the best rates and coverage options.
- Ask About Discounts: Inquire about any discounts you might qualify for, such as multi-policy discounts (bundling with your car or home insurance), safety course completion discounts, or even winter storage discounts.
- Read the Fine Print: Before signing anything, thoroughly review the policy documents. Understand what is covered, what is excluded, your deductible amounts, and your coverage limits. Don't be afraid to ask questions until you fully understand everything. [Massachusetts Insurance Worth Buying Anyway] truly means understanding its benefits.
Reviewing Your Policy Annually
Once you have an ATV or UTV insurance policy, don't just set it and forget it. Your needs, your machine's value, and market conditions can change. It's a good practice to review your policy annually, perhaps when you renew your registration or during your birthday month.
- Machine Changes: Have you added new accessories? Has your machine significantly depreciated? Have you bought a new machine entirely? Adjust your comprehensive and collision coverage to reflect the current value.
- Riding Habits: Are you riding more or less? Are you venturing into new types of terrain or participating in more organized events?
- Life Changes: Has your financial situation changed? Do you have more assets to protect, or perhaps fewer? Your liability limits might need adjustment.
- Shop Around Again: Every few years, it's wise to get new quotes from different insurers. You might find better rates or new coverage options from another provider.
Taking a proactive approach to your OHV insurance ensures you always have the right level of protection for your evolving needs and circumstances, allowing you to ride the beautiful Massachusetts trails with confidence and peace of mind.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws, prices and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.